# Interest Rate Model
Understand how Morpho markets calculate borrow and supply APY from interest rate models, including the AdaptiveCurveIRM behavior.
Source: https://docs.morpho.org/learn/concepts/irm
Morpho is an Interest Rate Model (IRM) agnostic protocol, meaning it can support any interest rate model for its markets. In Morpho, the interest borrowers pay in a given market is defined by the IRM chosen at market creation among a governance-approved set.
The only IRM that has been governance-approved is the [AdaptiveCurveIRM](#the-adaptivecurveirm), which is described in more detail later in this page.
## Understanding Borrow and Supply APY [#understanding-borrow-and-supply-apy]
The **Annualized Percentage Yield (APY)** is a critical metric that standardizes interest rates over a one-year period by accounting for compounding. In the context of lending protocols, two key APYs are:
* **Borrow APY:** This reflects the effective annual interest cost that borrowers incur. It is derived from the instantaneous interest rate provided by the chosen Interest Rate Model (IRM). Essentially, the Borrow APY tells borrowers how much they will pay on an annual basis for borrowing assets.
* **Supply APY:** This indicates the effective annual yield that lenders receive on their supplied assets. It is derived from the same per-second borrow rate, scaled by the market's utilization and by the share of interest left to suppliers after the market's fee, then compounded over a year.
### How Are These APYs Calculated? [#how-are-these-apys-calculated]
### Borrow APY Calculation [#borrow-apy-calculation]
The Borrow APY is obtained by compounding the per-second borrow rate over the entire year. The formula is:
$$
\text{borrowAPY} = \left(e^{\left(\text{borrowRate} \times \text{secondsPerYear}\right)} - 1\right)
$$
Here, `borrowRate` is the rate provided by the IRM and `secondsPerYear` equals 31,536,000.
### Supply APY Calculation [#supply-apy-calculation]
Suppliers receive the borrowers' interest minus the market's fee, spread over all supplied assets. Apply utilization and the fee to the per-second borrow rate first, then compound the resulting per-second supply rate over the year:
$$
\text{supplyRate} = \text{borrowRate} \times \text{utilization} \times (1 - \text{fee})
$$
$$
\text{supplyAPY} = \left(e^{\left(\text{supplyRate} \times \text{secondsPerYear}\right)} - 1\right)
$$
Where:
* **Utilization:** Is the ratio of the total borrowed assets to the total supplied assets.
* **Fee:** The market's fee, set per market by governance. (Scaled by [WAD: 1e18](https://github.com/morpho-org/morpho-blue/blob/main/src/interfaces/IMorpho.sol#L94C36-L94C50))
Do not multiply the Borrow APY by utilization and `(1 - fee)`: compounding is not linear, so scaling the APY after compounding overstates the Supply APY. With the example below (4.89% Borrow APY, 85% utilization), that shortcut gives 4.15% instead of 4.14%.
Below is a basic typescript snippet showcasing the rate calculus with a rate returned by the IRM of `1512768697`
```typescript
/**
* Calculate borrow APY using the exponential formula: exp(rate * seconds) - 1
* Where:
* - rate is the interest rate per second (in Wei with 18 decimals)
* - seconds is the number of seconds (typically for a year: 31536000)
*
* @param ratePerSecond Interest rate per second in Wei (18 decimals)
* @param seconds Number of seconds (typically a year: 31536000)
* @returns The borrow APY as a decimal (e.g., 0.0489 for 4.89%)
*/
function calculateBorrowRate(ratePerSecond: string, seconds: number): number {
// Convert rate to a number with 18 decimal precision
const rate = Number(ratePerSecond) / 1e18;
// Calculate exp(rate * seconds) - 1
const result = Math.exp(rate * seconds) - 1;
return result;
}
/**
* Calculate supply APY from the per-second borrow rate, utilization, and fee
* Formula: supplyAPY = exp(borrowRate * utilization * (1 - fee) * seconds) - 1
*
* @param ratePerSecond Borrow rate per second in Wei (18 decimals)
* @param utilization The utilization rate as a decimal (e.g., 0.8 for 80%)
* @param fee The fee rate in Wei (18 decimals, e.g., "0" for no fee)
* @param seconds Number of seconds (typically a year: 31536000)
* @returns The supply APY as a decimal (e.g., 0.0414 for 4.14%)
*/
function calculateSupplyAPY(
ratePerSecond: string,
utilization: number,
fee: string,
seconds: number
): number {
// Convert rate and fee from Wei to decimal (1e18 denominator)
const borrowRate = Number(ratePerSecond) / 1e18;
const feeRate = Number(fee) / 1e18;
// Apply utilization and fee to the per-second rate, then compound
const supplyRate = borrowRate * utilization * (1 - feeRate);
return Math.exp(supplyRate * seconds) - 1;
}
// Shared example values
const secondsInYear = 31536000;
const ratePerSecond = "1512768697"; // Rate per second in Wei (18 decimals)
const utilization = 0.85; // 85% utilization
const fee = "0"; // No fee (0 in Wei / 18 decimals)
// Calculate borrow APY
const borrowAPY = calculateBorrowRate(ratePerSecond, secondsInYear);
// Calculate supply APY
const supplyAPY = calculateSupplyAPY(
ratePerSecond,
utilization,
fee,
secondsInYear
);
// Display results
console.log(`Borrow APY: ${(borrowAPY * 100).toFixed(2)}%`);
console.log(
`Supply APY: ${(supplyAPY * 100).toFixed(2)}% at ${(
utilization * 100
).toFixed(0)}% utilization with ${(Number(fee) / 1e18) * 100}% fee`
);
```
The output here is:
```
Borrow APY: 4.89%
Supply APY: 4.14% at 85% utilization with 0% fee
```
### APY Conventions [#apy-conventions]
Between two interactions with a market, its borrow rate keeps moving: the AdaptiveCurveIRM's rate at target drifts with utilization until the next interaction accrues interest. An APY therefore depends on which borrow rate of that interval it uses. The formulas above stay the same; only `borrowRate` changes:
* **End-of-interval:** the borrow rate at the given timestamp, after drifting since the market's last update. It is the rate that applies from that moment on.
* **Interval average:** the average borrow rate between the market's last update and the given timestamp. It is the rate Morpho charges when it accrues interest over that interval.
Both are equal when the market was updated in the same block, and the gap grows with the time since the last update.
| Field or method | Convention |
| :---------------------------------------------------------------------------------------------------------------- | :----------------------------------------------------------------- |
| AdaptiveCurveIRM `borrowRateView` and `borrowRate` | Interval average, from the market's `lastUpdate` to the block time |
| SDK `Market.getBorrowApy(timestamp)`, `Market.getSupplyApy(timestamp)`, and the `borrowApy` / `supplyApy` getters | End-of-interval |
| SDK `Market.getAvgBorrowApy(timestamp)` and `Market.getAvgSupplyApy(timestamp)` | Interval average |
### Resources [#resources]
For a deeper dive into the mechanics and the code behind these calculations, refer to the following resources:
* [**Interest Rate Model Repository**](https://github.com/morpho-org/morpho-blue/tree/main/src/periphery/adaptive-curve-irm): Explore the implementation and the smart contracts that power the IRM.
* [**IRM Interface Documentation**](https://github.com/morpho-org/morpho-blue/blob/main/src/interfaces/IIrm.sol): Review the interface definitions and understand how different IRMs integrate into the system.
* [**Introducing the AdaptiveCurveIRM**](https://morpho.org/blog/introducing-the-adaptivecurveirm-efficient-and-autonomous/) article
This integrated approach ensures that both borrowers and suppliers have a clear understanding of the cost of borrowing and the returns on lending, all derived from a robust and governance-approved interest rate model.
Initially, this set is composed of one immutable IRM, the AdaptiveCurveIRM.
## The AdaptiveCurveIRM [#the-adaptivecurveirm]
### Overview [#overview]
The AdaptiveCurveIRM is engineered to maintain the ratio of borrowed assets over supplied assets, commonly called utilization, close to a target of 90%.
In Morpho, the collateral supplied is not rehypothecated. Removing this systemic risk removes the liquidity constraints imposed by liquidation needs. It enables more efficient markets with higher target utilization of capital and lower penalties for illiquidity, resulting in better rates for both lenders and borrowers.
As with every parameter of a Morpho Market, the IRM address is immutable. This means that neither governance nor market creators can change it at any given time. As such, the AdaptiveCurveIRM is designed to adapt autonomously to market conditions, including changes in interest rates on other platforms and, more broadly, any shifts in supply and demand dynamics.
Its adaptability enables it to perform effectively across any asset, market, and condition, making it highly suitable for Morpho's permissionless market creation.
### How It Works [#how-it-works]
The model can be broken down into two complementary mechanisms:
1. **The Curve Mechanism**
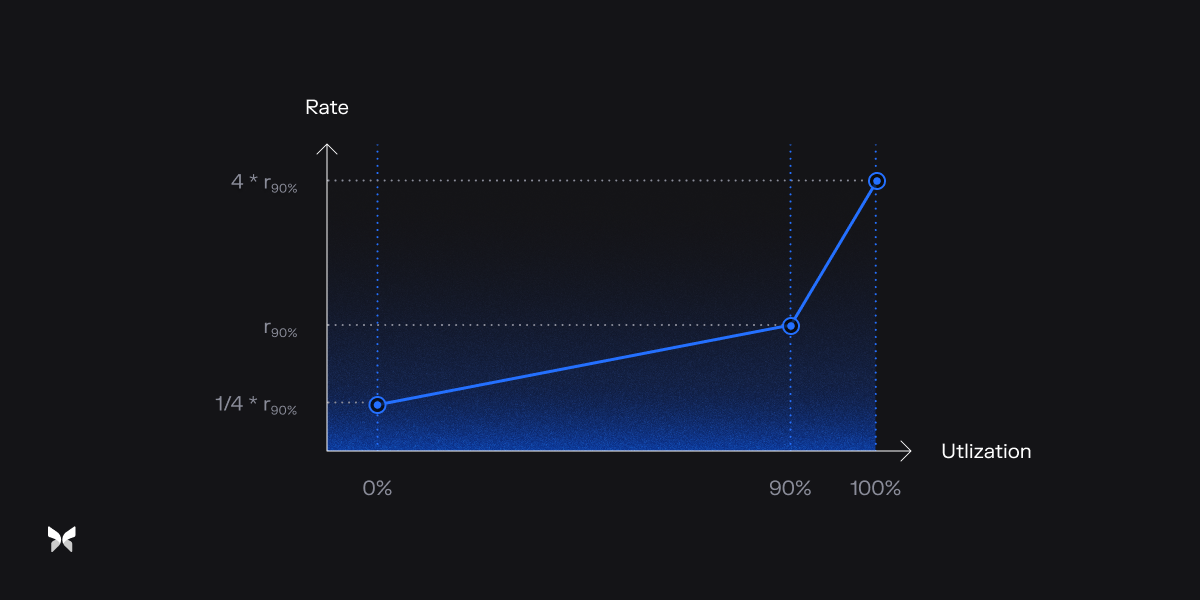
This mechanism is akin to the interest rate curve in traditional lending pools. It manages short-term utilization effectively, maintaining capital efficiency while avoiding excessively high utilization zones that could lead to liquidity issues.
$$
r_{90\%} \text{ is the target rate at utilization target } u_{target}=0.9
$$
Example with the interest rate currently at 4% at
$$
u_{target}=0.9
$$
* If utilization rate goes to 100% following a market event, the interest rate will instantly go to 16% in this example (x4)
* At the opposite, if a market event bring the utilization rate to 0%, the interest rate will instantly go to 1% in this example (/4)
2. **The Adaptive Mechanism**
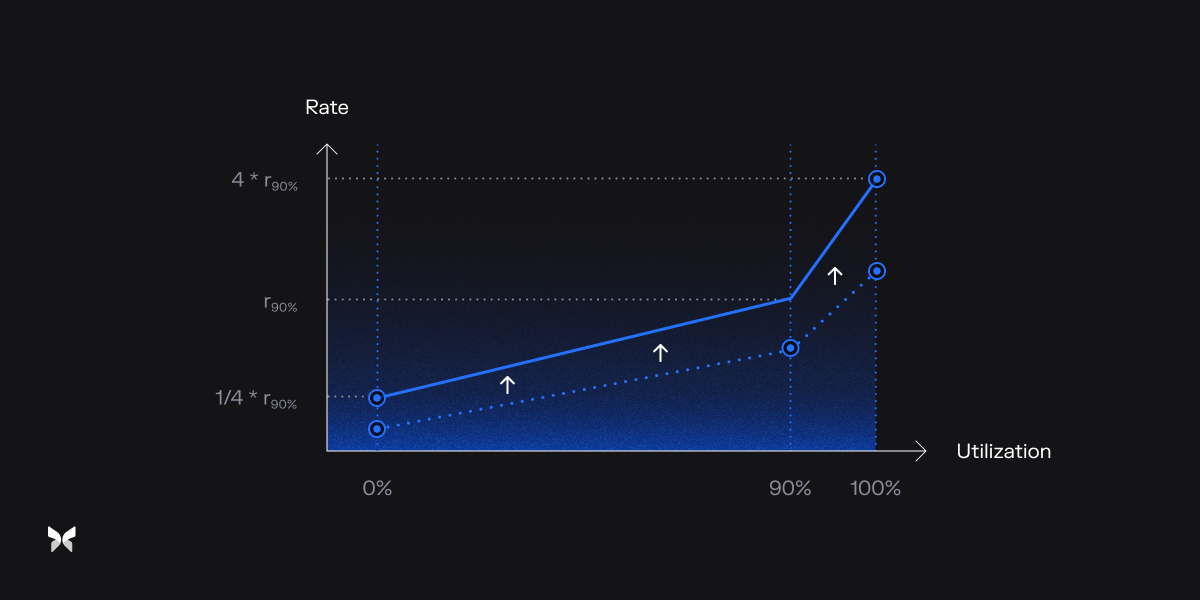
This mechanism fine-tunes the curve over time to keep the range of rates in sync with market dynamics. It achieves this by adjusting the value of the target rate, which in turn shifts the entire curve:
* When utilization exceeds the target, the curve continuously shifts upward. This incentivizes loan repayment and thus decreases utilization.
* When utilization falls below the target, the curve continuously shifts downward. This incentivizes borrowing and thus increases utilization.
The speed at which the curve adjusts is determined by the distance of current utilization to the target: the further it is, the faster the curve shifts.
This incremental adjustment of the curve allows for rate exploration, ultimately stabilizing when the interest rate at the target utilization aligns with the market equilibrium.
Some examples are given below about the target
$$
r_{90\%}
$$
* If the utilization remains at 45%, it will progressively decrease until it is divided by 2 after 10 days.
* If the utilization remains at 95%, it will progressively increase until it doubles after 10 days.
* If the utilization remains at 100%, it will progressively increase until it doubles after 5 days. This is the maximum speed at which it can move.
Here's a video showing how the two mechanisms combine to adjust interest rates:
For more on the AdaptiveCurveIRM, explore the [technical reference](/developers/contracts/irm/).